ServicesInsurance Claims
Insurance Claims Help in Yosemite Lakes
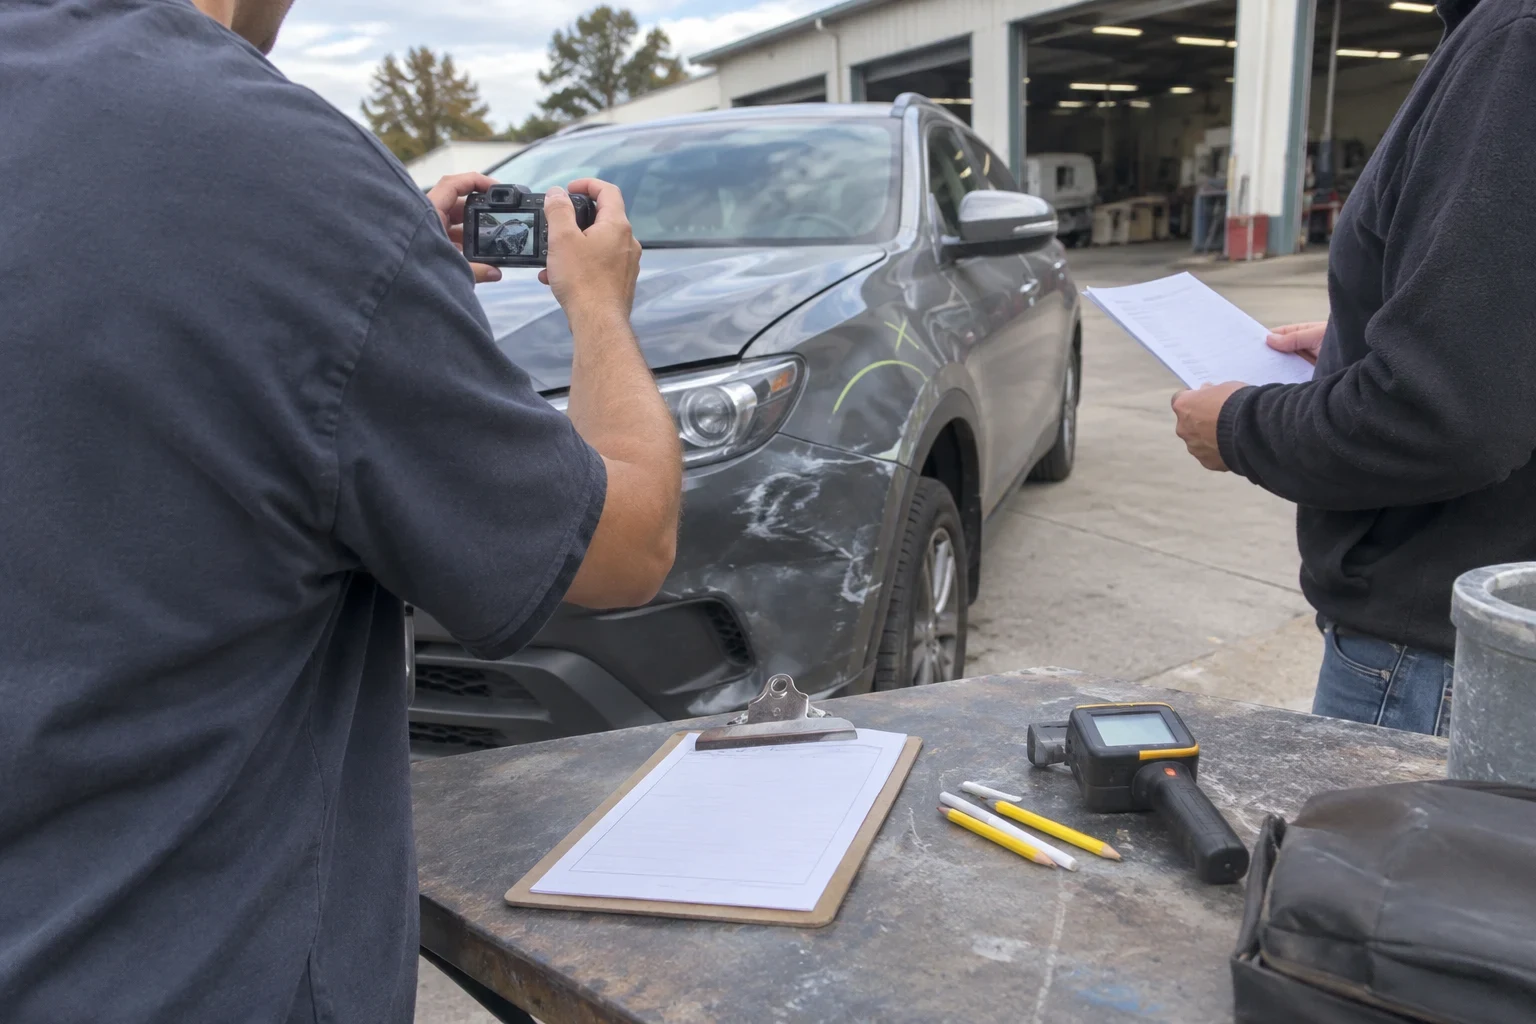
An insurance claim after a collision comes with paperwork full of codes and labor hours. We inspect your car, write the repair estimate, send the adjuster photos of what we find and explain each line so you know exactly what is being fixed and why.
What we handle on a claim, and what stays with your insurer
Every insurance claim has three sides: you, the insurance company and the shop that repairs your car. Our side is the repair. We inspect the damage, write a line-item estimate, compare it with the adjuster's appraisal and document anything the first look missed. We are not your adjuster, and coverage decisions stay between you and your insurer.
What we can do is translate. An appraisal uses shorthand like R&I (remove and install), R&R (remove and replace), blend time and refinish hours. We go through it with you line by line, so you can see which panels are being replaced, which are being repaired and why the total may change once the car is apart.
California rules let you choose where your vehicle is repaired. An insurer may suggest a shop, but you are not required to use it.
What our claim work includes
- Inspection with photos
- We photograph the impact point, every damaged panel and the parts that moved behind it, such as the bumper reinforcement, energy absorber and headlamp mounts. Those photos travel with the estimate so the adjuster sees what we see.
- Line-item repair estimate
- Each part, each labor operation and the paint materials are listed separately. You can set it beside the insurer's appraisal and spot exactly where the two differ.
- Supplements for hidden damage
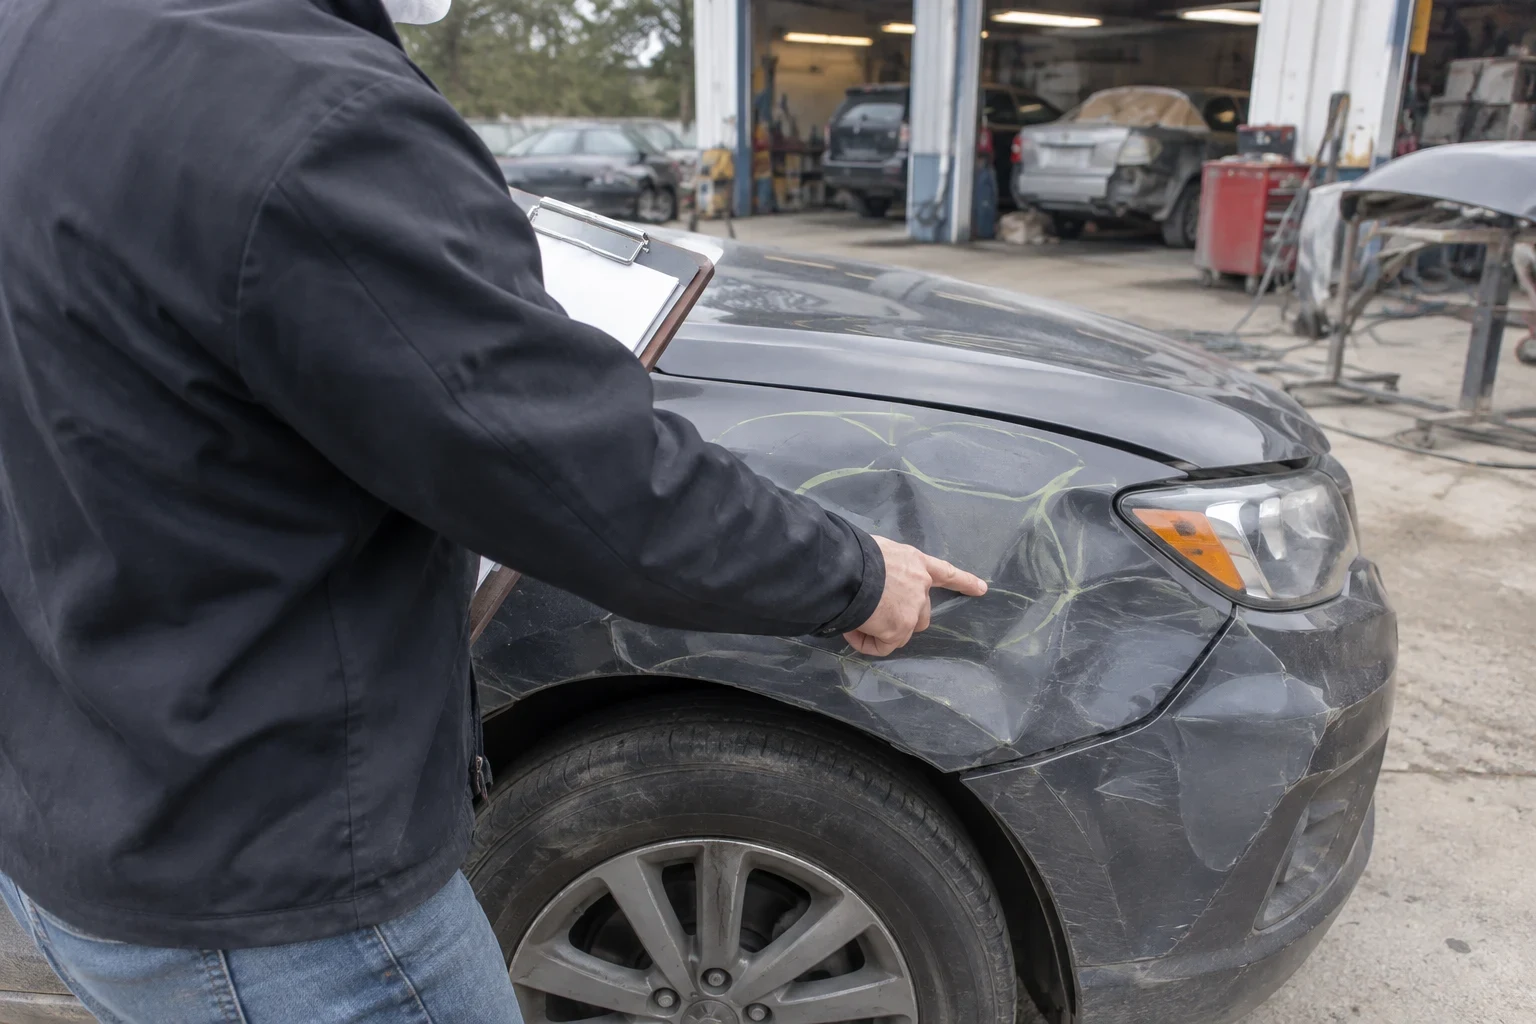
- A front hit often cracks the radiator support or pushes back the A/C condenser, and none of that shows until the bumper cover comes off. When teardown turns up more, we stop, photograph it and send a supplement to the insurer before doing the added work.
- Parts choices explained
- Estimates can list OEM parts from the carmaker, aftermarket parts or used parts pulled from another vehicle. We tell you which ones are on your estimate and how each fits and finishes.
- Refinish backed by a warranty
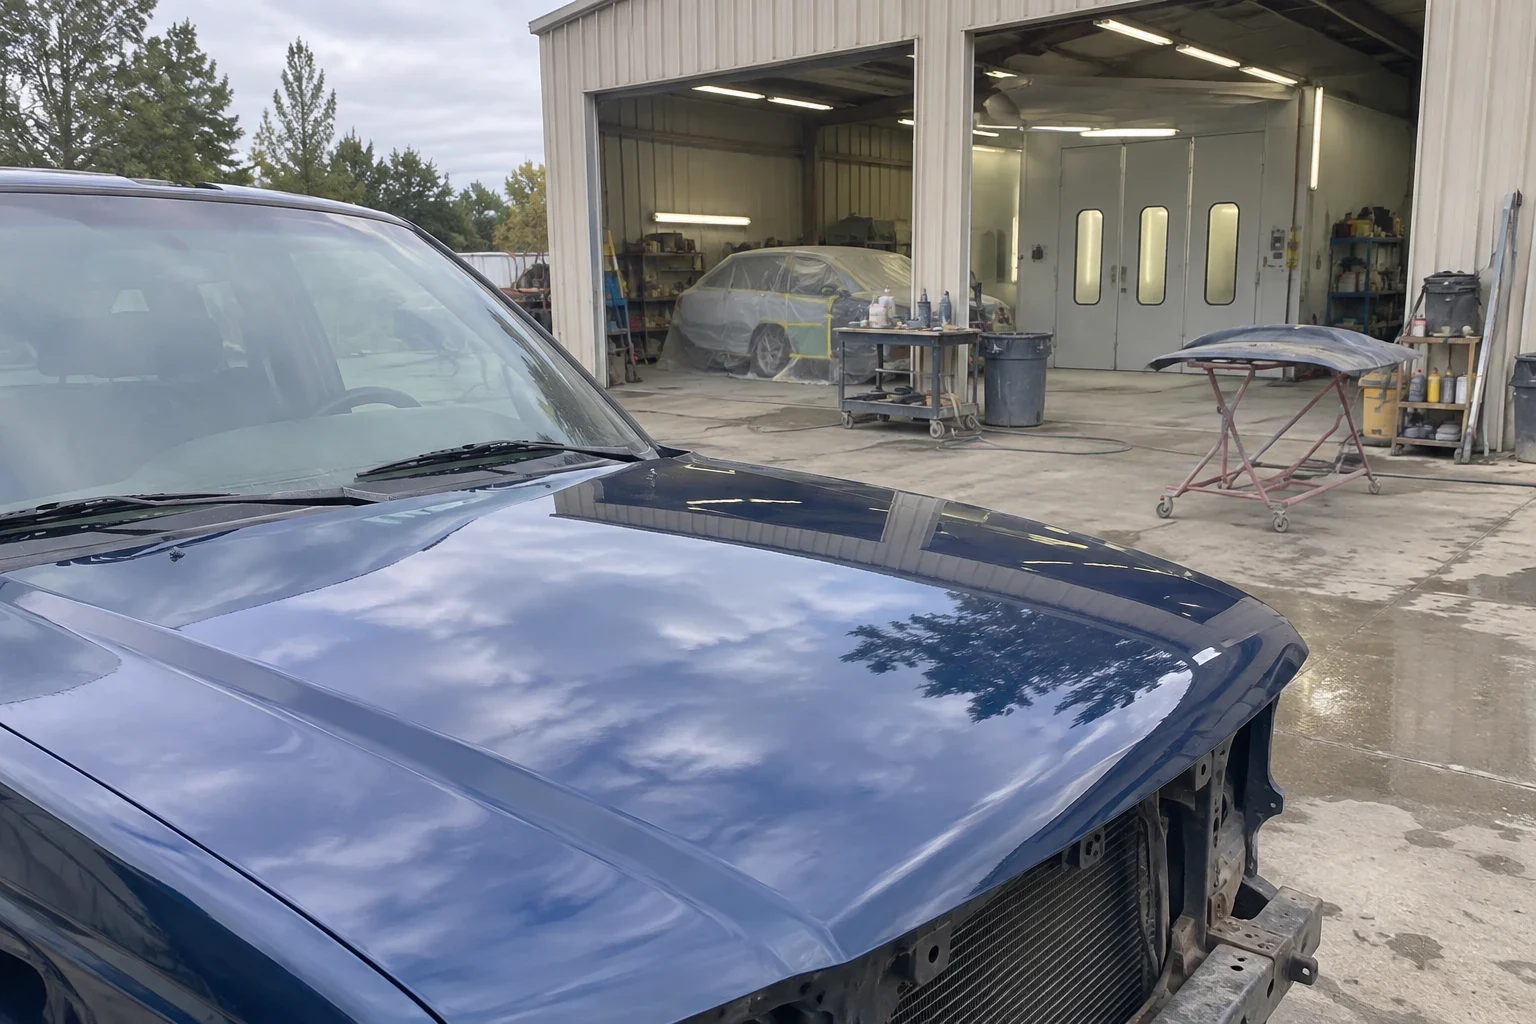
- We match the factory color and blend into the panels next to the repair so the new paint does not stand out in daylight. All of our paint work carries a lifetime warranty.
Signs your claim deserves a closer look
The appraisal came from photos only
Phone-photo estimates catch the visible scuffs and miss what is behind the plastic. Expect the number to grow once the car is torn down.
Only the bumper cover is listed after a hard hit
A cover is a plastic skin. If the impact was strong enough to crack it, check the reinforcement bar, brackets and sensors behind it, which our Bumper Repair page covers in detail.
Doors, hood or trunk close differently
Uneven panel gaps or a door that now needs a slam point to shifted structure. That calls for measurement and possibly frame straightening, and it should be on the claim before work starts.
No blend time on the estimate
Without blending, a new door painted beside an original fender can look a shade off. A missing blend line is worth asking about.
You are unsure whether to file at all
A deer strike on a foothill road around Coarsegold can look minor and still crack a grille, headlamp and radiator. A real estimate tells you how the repair compares with your deductible.
How a claim repair moves through our shop
- 1
Phone call first
Tell us your insurer, your claim number if you have one and what happened. We let you know what paperwork to bring and when to drop off your vehicle.
- 2
Inspection and estimate
We look the car over at our shop, photograph the damage and write our estimate. If the adjuster has already sent an appraisal, we go over the differences with you.
- 3
Approval and teardown
Once the insurer approves the repair, we disassemble the damaged area. Anything new gets photographed and sent as a supplement, and we call you before that work goes ahead.
- 4
Repair, refinish and pickup
We repair or replace the parts, refinish and check panel gaps and lights. At pickup we compare the final invoice to the approved estimate with you, and you pay your deductible to the shop.
What decides your out-of-pocket cost
On a covered claim, the insurer pays the approved repair and you pay your deductible. What you end up paying depends on your policy, who was at fault and what the car turns out to need once it is apart. We cannot set coverage, but we can show you where each number comes from.
- Deductible and coverage type
- Collision coverage on your own policy usually carries a deductible. If the other driver's insurer accepts fault, their liability coverage may pay the repair instead.
- Damage found at teardown
- Hidden damage raises the repair total through a supplement. If it is approved, the insurer covers it, not you.
- Parts on the estimate
- Your policy may specify aftermarket or used parts. If you want OEM parts the policy does not include, you may pay the difference.
- Paint and blending
- Tri-coat pearls and metallic colors take more material and more blending than solid colors, which moves the refinish portion of the estimate.
Straight answers about filing and fixing
Something not covered here? (559) 616-8794
My insurer pointed me to a particular body shop. Can I take my car somewhere else?
Yes. California leaves the choice of repair shop to you, not the insurance company. A referral is only a suggestion, and you can bring your vehicle to us and we will work from the same claim.
Is it better to file a claim or just pay for the repair out of pocket?
The call is yours, and it usually comes down to how the repair total compares with your deductible and what a claim might do to your policy. We can write a full estimate first so you are deciding with a real number in hand. Your agent is the right person to ask about premiums.
What if more damage turns up once the car is apart?
We stop, photograph what we found and send a supplement to the insurer for approval. We also phone you and explain why the total moved. Nothing outside the approved estimate gets done and then sprung on you at pickup.
Will you deal with the adjuster on my behalf?
We handle the repair side: the adjuster gets our photos, our estimate and any supplements, and we answer their questions about the work. Decisions on coverage, fault and rental cars belong to the insurer, so those conversations still happen between you and them.
Does the paint warranty still apply after the claim is closed?
It does. Every bit of our paint work carries a lifetime warranty, no matter whether the insurer paid for the repair or you paid for it yourself.
Bring the paperwork and the car, we'll explain both
Have your claim number and any appraisal you received ready. We will go through the damage and the estimate with you before any work begins.